Trump’s Bombardier Threat Signals a New Risk for Global Manufacturers: Build Local or Lose Market Access

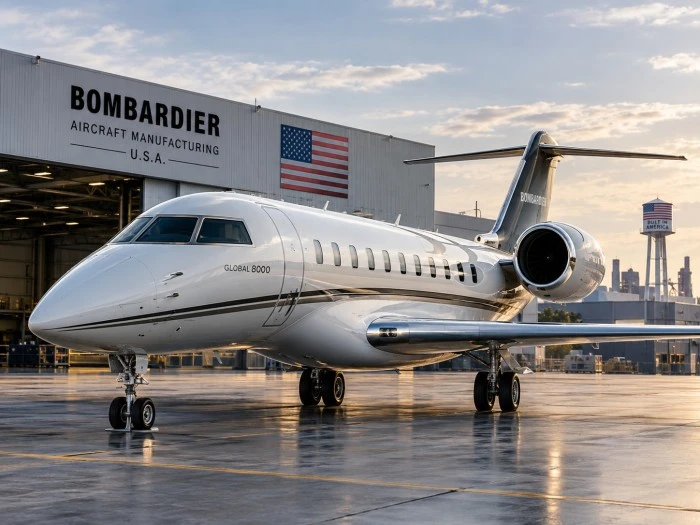
President Donald Trump has threatened to stop Canadian aircraft maker Bombardier from selling planes in the United States unless it manufactures them there, turning a trade dispute into a corporate-location question. (reuters.com, apnews.com) The immediate issue is Bombardier, but the larger risk is for multinational companies that have built production networks around efficiency rather than political geography.
Bombardier already has thousands of U.S. workers and roughly 2,800 American suppliers across 47 states. (rss.globenewswire.com) The executive question is no longer simply whether to reshore production; it is how much capital companies should commit to preserve market access when governments can change the rules.
BOARDROOM BRIEFING: What Executives Need to Know
- Bombardier: Trump’s threat links access to the U.S. market directly to domestic manufacturing, although no formal mechanism for implementing the restriction has been disclosed. (reuters.com)
- Supply Chain: Bombardier says it works with approximately 2,800 American companies across 47 states and spends more than $2.5 billion annually with U.S. suppliers. (rss.globenewswire.com)
- Localization: Moving production can require new facilities, tooling, labor, certification, supplier qualification, inventory and duplicated capacity.
- Market Access: Government policy is becoming a more important variable in manufacturing-footprint decisions, alongside labor, logistics and production costs.
- Capital Allocation: A low-cost production location can become an expensive strategic choice if political intervention puts revenue at risk.
- Resilience: Domestic final assembly does not eliminate exposure to foreign components, technology, materials or suppliers.
- Precedent: The Bombardier dispute gives boards in aerospace, automotive, semiconductors, pharmaceuticals and energy a concrete case for reassessing geopolitical manufacturing exposure.
Trump’s Bombardier Ultimatum Changes the Market-Access Equation
Trump’s Bombardier statement creates a market-access risk, but it is not yet an implemented U.S. sales ban. Trump said on September 7 that Bombardier would no longer be allowed to sell aircraft in the United States unless it started manufacturing there. Reuters reported that the administration had not specified how the restriction would be enforced. (reuters.com)
That distinction matters for executives. A presidential statement can alter expectations immediately, but a legally enforceable restriction requires an identifiable policy mechanism. Boards should not model a confirmed prohibition when the administration has not yet established the mechanism, scope or timeline.
The timing is also significant. Canada imposed retaliatory tariffs covering about $20 billion of U.S. goods on September 8, escalating the trade confrontation between Washington and Ottawa. (apnews.com) The Bombardier threat arrived inside that broader dispute, making the company a potential instrument of trade policy rather than simply a participant in an ordinary commercial disagreement.
For companies operating internationally, the lesson is direct: policy risk can become operational risk before a regulation formally takes effect.
Bombardier Shows Why “Foreign Manufacturer” Is an Incomplete Label
Bombardier is not simply a Canadian manufacturer selling foreign-built aircraft into America; its operations are deeply integrated with the U.S. industrial base. Bombardier says its American supply chain includes approximately 2,800 companies across 47 states, while its U.S. operations span more than 20 states. (rss.globenewswire.com)
The company also says it spends more than $2.5 billion annually with U.S. suppliers. Its U.S. footprint includes wing production in Texas, flight-control production near Los Angeles and a significant operation in Wichita, Kansas. (rss.globenewswire.com)
That structure makes the dispute economically complicated. Restricting Canadian-built Bombardier aircraft could affect American suppliers, workers and service operations alongside the Canadian parent company.
Bombardier’s own economic data illustrates the integration. Its 2024 footprint report said its Canadian operations accounted for approximately US$2.4 billion in supplier spending from the United States and Mexico. (bombardier.com)
This is where global supply-chain resilience becomes a board-level issue. Production is rarely divided neatly along national borders. An aircraft may be assembled in one country, use engines and systems produced in another, and depend on suppliers scattered across several jurisdictions.
The Hidden Cost of “Build Local” Goes Beyond a New Factory
The cost of localization is the total incremental expense required to shift production capacity closer to the market, not simply the price of constructing a factory.
For a company such as Bombardier, a meaningful localization program could involve:
- New or expanded manufacturing facilities
- Production tooling and equipment
- Skilled-worker recruitment and training
- Supplier qualification and relocation
- Additional inventory and logistics capacity
- Regulatory and certification work
- Duplicate production lines during the transition
- Higher fixed costs while volumes ramp
The financial question is not whether American production is technically possible. It is whether the localization premium is lower than the revenue and strategic value exposed by losing U.S. market access.
That calculation changes with scale. A company generating a large percentage of revenue from one market can rationally accept higher production costs to protect that market. A company with diversified revenue may instead decide that duplication is economically inefficient.
Executives should also account for the opportunity cost. Capital committed to a politically motivated second production footprint cannot simultaneously fund acquisitions, automation, R&D, debt reduction or shareholder returns.
The best manufacturing localization strategy is not automatically the one with the most domestic production. It is the one that produces an acceptable risk-adjusted return.
From Tariffs to Market Access: The New Geopolitical Risk Framework
Geopolitical manufacturing risk should be modeled as an operating variable that directly affects revenue, costs, capacity and capital allocation.
A board-level framework should track five policy channels:
- Tariffs: Additional costs imposed on imported products or components.
- Quotas: Limits on the volume of goods that can enter a market.
- Certification restrictions: Regulatory decisions that can prevent products from being sold.
- Local-content requirements: Rules tying market access or incentives to domestic production.
- Procurement exclusions: Government purchasing policies that favor domestic suppliers.
Model Policy Risk as an Operating Variable, Not a Political Headline
A geopolitical risk model should translate government action into measurable financial exposure.
CFOs and COOs can build scenarios around three variables: probability, financial impact and response cost.
For example:
Expected exposure = Probability of restriction × Revenue at risk + incremental operating cost.
That calculation should then be compared with the cost of mitigation. Mitigation might mean a new factory, a second supplier, additional inventory, regional assembly or contractual restructuring.
The purpose is not to predict politics. It is to determine when management should act before political uncertainty becomes a supply-chain disruption.
Measure the “Localization Premium”
The localization premium is the incremental cost a company accepts to reduce geopolitical exposure and protect access to a strategic market.
A useful executive dashboard should compare:
| Variable | Executive question |
|---|---|
| Revenue at risk | How much sales could be affected? |
| Production cost | How much more expensive is regional production? |
| Capex | What investment is required? |
| Time to capacity | How quickly can replacement capacity operate? |
| Supplier exposure | Which critical inputs remain foreign-dependent? |
| Policy probability | How likely is the restriction? |
| Reversibility | Can the investment be redeployed if policy changes? |
That final variable is frequently overlooked. A $1 billion factory is not the same strategic decision if it can serve several markets than if it exists solely to satisfy one government’s policy demand.
The Contrarian Case: Reshoring Does Not Automatically Mean Resilience
Reshoring does not guarantee supply-chain resilience because domestic assembly can still depend on foreign components, technologies, materials and suppliers.
Bombardier makes the point unusually clearly. Its aircraft rely on U.S.-made engines from companies including GE Aerospace and Honeywell Aerospace, while the broader company maintains substantial manufacturing and service activity in both countries. (apnews.com)
The same principle applies far beyond aerospace. A semiconductor manufacturer can build a U.S. fab while depending on foreign equipment. A pharmaceutical company can produce medicines domestically while sourcing active ingredients internationally. An automotive company can assemble vehicles locally while relying on overseas battery materials.
The location of final assembly is only one layer of supply-chain exposure.
This is why enterprise procurement strategy should map dependencies below the first tier. A supplier that appears domestic may itself depend on foreign components, specialized machinery or raw materials.
Boards that treat “Made in America” as synonymous with resilience risk confusing geographic proximity with system redundancy.
Bombardier’s Next Move Is a Capital-Allocation Test for Global CEOs
Bombardier’s strategic response will demonstrate whether companies can preserve market access without rebuilding their entire manufacturing model.
The company has several potential paths:
- Expand U.S. manufacturing to satisfy political and commercial pressure.
- Increase capacity at existing American facilities rather than duplicate the entire production system.
- Seek regulatory or trade accommodations before committing major capital.
- Regionalize production so different markets receive products from strategically aligned facilities.
- Maintain the current structure while accepting greater policy risk.
- Create a dual-footprint model that provides additional flexibility at a higher fixed cost.
Bombardier’s recent factory decisions add complexity. The company announced on September 1 that it would acquire a Canadian facility from Mitsubishi Heavy Industries producing wings for its Global 5500 and 6500 aircraft. (bombardier.com)
That move underscores the tension facing executives: companies are still making industrial investments based on engineering capability, workforce specialization and production economics even as governments increasingly emphasize national manufacturing.
For boards, cross-border M&A and manufacturing expansion should now be evaluated through a second lens: What happens if market-access rules change after we invest?
The Strategic Playbook: How CEOs Should Price Geopolitical Manufacturing Risk
CEOs should treat geopolitical manufacturing exposure as a measurable portfolio risk and establish predefined triggers for changing production or sourcing decisions.
1. Map revenue concentration by jurisdiction
Identify the markets that account for the largest share of revenue and profit. A company with 40% of sales concentrated in one jurisdiction has a different localization threshold from one with globally distributed demand.
2. Map critical suppliers below Tier 1
Do not stop with direct vendors. Identify critical Tier 2 and Tier 3 dependencies, especially components that cannot be replaced quickly.
3. Assign probability-weighted policy scenarios
Build at least three scenarios:
- Base: Current rules remain broadly intact.
- Pressure: Tariffs, quotas or local-content requirements increase costs.
- Restriction: Market access becomes conditional on domestic production.
4. Calculate revenue-at-risk versus localization cost
Management should compare the value of protected revenue against the full cost of regional capacity. Include capex, operating expenses, duplicated capacity and financing costs.
5. Establish decision triggers
Create measurable thresholds that automatically bring the issue back to the board.
For example, a company might trigger a capacity review when projected policy exposure exceeds a defined percentage of annual operating profit or when alternative capacity can be built within the remaining policy-risk window.
This is executive decision-making under uncertainty in practical form: management does not need to predict the next political announcement. It needs a predefined response when the economics cross a threshold.
Executive Outlook: Market Access Is Becoming Part of the Manufacturing Footprint
Market access is increasingly becoming a component of manufacturing strategy, alongside cost, labor, logistics, technology and supplier availability.
The Bombardier dispute does not prove that globalization is ending. It demonstrates something more practical: the economic value of a production location now depends partly on the political stability of the market it serves.
That changes the capital-allocation equation.
A plant in the lowest-cost jurisdiction may no longer be the best investment if access to the destination market can be restricted. At the same time, indiscriminate reshoring can destroy returns by duplicating capacity that does not need to exist.
The strongest operating model may be neither full globalization nor full localization. It may be regional optionality: enough production, supplier diversity and regulatory flexibility to absorb policy shocks without rebuilding the company from scratch.
For CEOs, CFOs and COOs, the Bombardier case presents a useful test.
Ask three questions before approving the next major manufacturing investment:
Where is our revenue most politically exposed?
How quickly could we replace a critical production or supplier node?
What would it cost to preserve market access if the rules changed?
Companies that can answer those questions before a trade dispute reaches their own industry will have a meaningful advantage over those forced to react afterward.